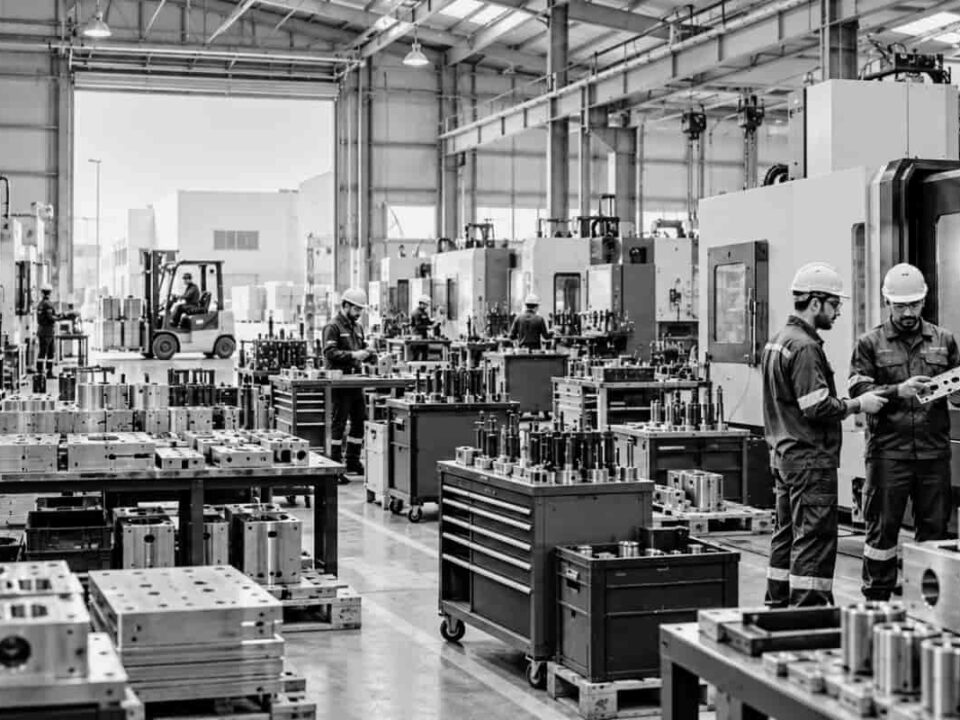
Facility selection should be reviewed alongside the licence and activity rather than left until the end of the application process.
ADAFZ COMPANY SETUP PROCESS
ADAFZ’s current website presents the setup process in four broad stages: choosing the activity, adding a workspace, submitting documents and receiving the licence. For planning purposes, investors should approach the application as follows.
1. Define the Business Model
Prepare a clear description of what the company will do, where its customers will be located, how it will generate revenue and whether it will handle physical goods.
2. Select the Legal Structure
Decide whether to apply through an ADAFZ LLC or an available branch route based on the shareholder profile, governance requirements and operating model.
3. Confirm the Licensed Activities
Map the operating model to the activities available through ADAFZ and identify whether external approval is required.
4. Select the Facility
Choose a workspace appropriate for the approved activities and planned operations.
5. Prepare the Application Documents
Use the official ADAFZ checklist applicable to the selected structure and shareholder type.
6. Submit the Application
Submit the registration and licensing application through ADAFZ’s official application system with the required documents and information.
7. Complete Establishment Requirements
Following approval, complete the applicable licensing, workspace and related establishment requirements under the selected ADAFZ package.
The exact steps and sequence can vary by structure, activity, facility and applicant circumstances.
ADAFZ SETUP COST AND TIMING
ADAFZ setup costs depend on the selected legal structure, licensed activities, workspace, visa allocation and any additional regulatory or operational requirements. ADAFZ publishes business-package and facility information on its website, but a general package should not be treated as a complete estimate for every investor.
Processing depends on the application profile, supporting documents, workspace and any external approvals. Although ADAFZ publishes indicative application stages, businesses should not treat an advertised processing period as a guaranteed completion date.
For a relevant proposal, prepare a clear activity description, shareholder profile, preferred legal structure, required facility, anticipated staffing needs, requirement for mainland business and any regulated-activity considerations.
OPERATING OUTSIDE THE FREE ZONE
An ADAFZ licence should not be treated as unrestricted permission to conduct business throughout Abu Dhabi or the wider UAE mainland. The Abu Dhabi Department of Economic Development describes its Dual Licence as allowing establishments registered in Abu Dhabi free zones to conduct their activities and manage their business outside the free-zone area.
A Dual Licence may be relevant to an eligible ADAFZ company that needs to operate outside the free zone. However, the available activities, eligibility criteria and required approvals should be confirmed for the particular business.
CORPORATE TAX CONSIDERATIONS
ADAFZ should not be presented as automatically exempt from UAE Corporate Tax. An entity that meets and continues to meet the conditions for Qualifying Free Zone Person status may benefit from a 0% Corporate Tax rate on Qualifying Income. Under that regime, taxable income that is not Qualifying Income is subject to 9%, with the applicable de minimis rules and special income rules also taken into account.
Whether an ADAFZ entity qualifies depends on compliance with the UAE free-zone Corporate Tax conditions, including Qualifying Income, adequate substance, transfer pricing requirements and audited financial statements, where required under the applicable rules. Non-qualifying revenue must be assessed against the de minimis requirements. Failure to meet those requirements or other qualifying conditions can result in loss of QFZP status and taxation under the ordinary Corporate Tax regime.
Ministerial Decision No. 229 of 2025 identifies activities including manufacturing, processing, logistics services, specified aircraft financing and leasing, headquarters services to related parties, and distribution of goods or materials in or from a Designated Zone as Qualifying Activities. Each activity remains subject to the definitions, conditions and limitations in the decision, and its income is not automatically qualifying solely because of its activity label.
A business should assess its activities, customers, transactions, operating substance and income streams before determining its Corporate Tax treatment.
VAT AND DESIGNATED ZONE STATUS
The Federal Tax Authority’s List of Designated Zones includes Abu Dhabi Airport Free Zone from 1 January 2018, and Al Ain International Airport Free Zone and Al Butain International Airport Free Zone from 18 June 2018. The official FTA list uses the name Al Butain International Airport Free Zone, while ADAFZ’s current operational materials refer to Al Bateen Executive Airport as one of its three airport locations.
Designated Zone status does not create a blanket VAT exemption. VAT treatment depends on the relevant location, whether the transaction concerns goods or services, the movement and destination of goods, the parties to the transaction, the statutory conditions and the company’s records and compliance position. Confirm that the specific premises and transaction fall within the applicable designated-zone boundaries and rules; ADAFZ’s wider airport footprint should not be treated as automatically receiving identical VAT treatment.
DOCUMENTS TO PREPARE
ADAFZ provides separate official document checklists for LLC registration by individual shareholders, company registration and branch registration. Requirements vary by applicant type, and ADAFZ may request additional information.