
WAYS TO CONDUCT BUSINESS DURING RAMADAN
April 7, 2021
Why Saudi’s free zone move will add to the allure of the kingdom AS FEATURED ON Arabian Business – March 18, 2021
April 7, 2021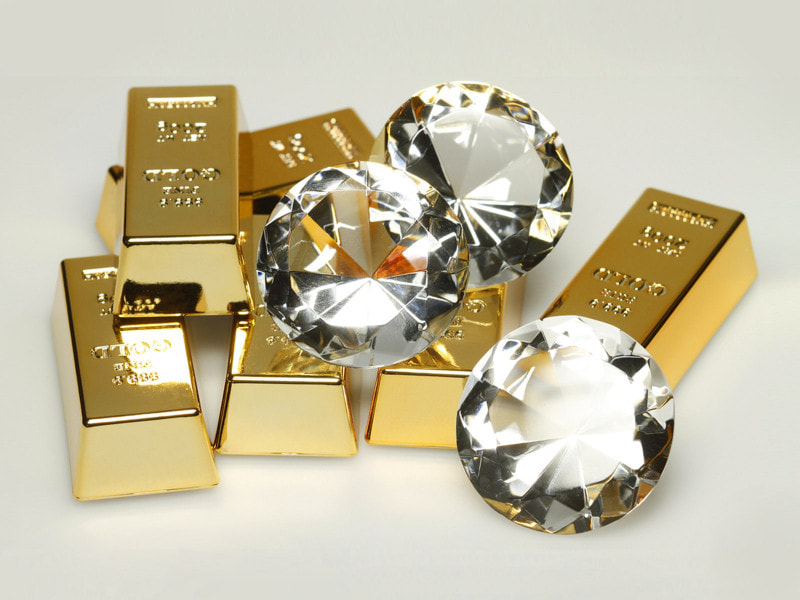
VAT On Gold And Diamonds In The UAE: Rules For Gold And Diamond Businesses
This article has been researched and written by Scott Cairns and the team at Creation Business Consultants.
Gold has always been a highly traded commodity in the UAE. Traders must be aware of the VAT impact on trading in gold, diamonds, and gold and diamond jewellery.
In Short
- Gold and diamond jewellery sold to consumers is subject to the standard 5% VAT on the full price, including making charges.
- Investment-grade gold, silver and platinum (99% purity or more, in a form tradeable in global bullion markets) is zero-rated.
- Since 25 February 2025, qualifying domestic supplies of specified precious metals, precious stones and jewellery between VAT-registered businesses may be subject to the reverse charge mechanism, provided the recipient intends to resell the Precious Goods or use them to produce or manufacture Precious Goods and the required declarations and supplier checks are completed (Cabinet Decision No. 127 of 2024).
- Tourists can claim back part of the VAT on eligible purchases through the Tax Refund for Tourists Scheme.
This article will cover the VAT impact on:
- Gold bars and investment-grade precious metals.
- Gold, diamond and gold and diamond jewellery.
- The reverse charge mechanism for precious metals and stones.
- Making charges.
- VAT refunds for tourists.
TRADING IN GOLD BARS AND INVESTMENT-GRADE PRECIOUS METALS
Under Article 45(1)(g) of Federal Decree-Law No. 8 of 2017 and Article 36 of its Executive Regulation, the supply or import of investment-grade precious metals is zero-rated, meaning it will have a zero rate of tax or VAT. Because these supplies are zero-rated, the reverse charge mechanism does not apply to them.
DEFINITION OF INVESTMENT GRADE PRECIOUS METALS
The phrase “investment precious metals” means gold, silver and platinum that meet the following standards:
- The metal is of a purity of 99 percent or more.
- The metal is in a form tradeable in global bullion markets.
Source: Article (36) Executive Regulation (VAT).
TRADING IN GOLD, DIAMOND AND GOLD AND DIAMOND JEWELLERY
Under Article 3 of Federal Decree-Law No. 8 of 2017, the VAT rate applicable to supplies of gold, diamond and gold and diamond jewellery to final consumers is the standard rate of 5%. However, qualifying domestic supplies between VAT-registered businesses may be subject to the reverse charge. Since 25 February 2025, this is governed by Cabinet Decision No. 127 of 2024, which replaced Cabinet Decision No. 25 of 2018 and extended the reverse charge from gold and diamonds to a wider range of precious metals and stones.
WHICH GOODS ARE COVERED BY THE REVERSE CHARGE?
Under Cabinet Decision No. 127 of 2024, the reverse charge applies to:
- Precious metals: gold, silver, platinum and palladium
- Precious stones: natural and synthetic diamonds, pearls, rubies, sapphires and emeralds
- Jewellery: items made from these metals or stones, where the value of the precious components exceeds the value of the other materials
Previously, the reverse charge covered only gold, diamonds and products where gold or diamonds were the principal component.
WHAT IS MEANT BY THE REVERSE CHARGE MECHANISM FOR COMMERCIAL GOLD AND DIAMOND TRADERS?
Under Cabinet Decision No. 127 of 2024, the responsibility of charging and collecting VAT has been moved from the supplier of precious metals, precious stones and jewellery to the purchaser, provided the purchaser is registered for VAT and gives the supplier written declarations, before the date of supply, stating that:
- The Recipient intends to resell the Precious Goods or use them to produce or manufacture Precious Goods.
- The Recipient is registered for VAT in the UAE.
- The purchaser then calculates and accounts for the VAT in its own VAT return, and the supplier does not charge VAT on the invoice.
RESPONSIBILITIES OF THE SUPPLIER OF GOODS TO APPLY REVERSE CHARGE MECHANISM
The supplier of goods is responsible to verify the registration of the purchaser. A supplier must comply with:
- Obtaining and retaining both written declarations from the purchaser or recipient.
- Verifying the registration of the purchaser in accordance with rules set by the Federal Tax Authority, for example using the FTA’s TRN verification tool.
- Keeping a copy of the declarations and showing on the tax invoice that the reverse charge applies.
WHEN THE REVERSE CHARGE DOES NOT APPLY
The reverse charge does not apply in the following cases:
- The purchaser is not registered for VAT, or does not provide the written declarations before the date of supply.
- The supply of goods is taxed at zero rate. Therefore, for investment-grade precious metals, and direct or indirect exports of Precious Goods that are zero-rated, the reverse charge mechanism will not apply.
- The goods are sold to consumers or to other buyers who are not purchasing them for resale or manufacturing. In this case, the supplier charges 5% VAT in the normal way.
CONSEQUENCES OF FAILURE TO COMPLY WITH REGULATIONS
Where a taxable domestic supply does not meet the conditions for the reverse charge, including where the Recipient does not provide the required declarations, the supplier must account for VAT under the normal rules. Where the reverse charge applies, the Recipient accounts for the VAT and is responsible for the tax obligations arising from the supply.
VAT ON MAKING CHARGES
Jewellery is often sold with a making charge for the design and manufacturing work.
- Sales to consumers: VAT at 5% applies to the full price, including the making charge.
- Single price between VAT-registered businesses: where the goods and making service are supplied for a single price, the reverse charge may apply to the whole supply only if they constitute a single composite supply: the precious goods are the principal component, the making service is ancillary or closely linked and not separately priced, and both are supplied by the same supplier.
- Making charge invoiced separately: the supplier is treated as making multiple supplies. Only the precious goods may qualify for the reverse charge; the making service is subject to the normal VAT rules and, where standard-rated, VAT at 5%.
The FTA’s public clarification VATP043 explains how to decide whether a supply is a single supply or multiple supplies, and which records to keep.
FREQUENTLY ASKED QUESTIONS
Is there VAT on gold in the UAE?
Yes. Gold jewellery sold to consumers is subject to 5% VAT, while investment-grade gold of 99% purity or more is zero-rated. Qualifying domestic supplies between VAT-registered traders may fall under the reverse charge where the recipient intends to resell the Precious Goods or use them to produce or manufacture Precious Goods, subject to the required declarations and supplier checks.
Is there VAT on gold bars in the UAE?
Gold bars of 99% purity or more, in a form tradeable in global bullion markets, are zero-rated, so no VAT is charged.
Do you pay VAT on making charges?
Yes. Consumers pay 5% VAT on the full price, including the making charge. Between VAT-registered businesses, the treatment depends on whether the making charge is part of a single price or invoiced separately.
Can tourists get a VAT refund on gold in Dubai?
Yes. Tourists can claim a refund through the Tax Refund for Tourists Scheme when buying from a participating retailer, spending at least AED 250 (excluding VAT) and validating the purchase at the exit point within 90 days. The refund is 85% of the VAT paid, minus a small fee.
Does the reverse charge apply to diamonds and other precious stones?
Yes. Since 25 February 2025, the reverse charge covers natural and synthetic diamonds, pearls, rubies, sapphires and emeralds, as well as gold, silver, platinum and palladium, when supplied between VAT-registered businesses for resale or manufacturing.
What changed with Cabinet Decision No. 127 of 2024?
It replaced Cabinet Decision No. 25 of 2018 from 25 February 2025. It extended the reverse charge to more precious metals and stones, requires two written declarations from the buyer, and removed joint liability between supplier and buyer.
CONCLUSION
The reverse charge provides great relief on the cash flow of gold and diamond traders who are dealing in high-value goods, who are exporting and who may be having longer payment terms with their customers.
It will further allow investors in gold and diamond trading to continue their business with ease, thereby stabilising this market. With the reverse charge now covering a wider range of precious metals and stones, traders should review their invoicing, declarations and VAT return processes.
Should you wish to know more about Creation Business Consultants’ VAT services in Dubai, Abu Dhabi and the UAE or require a free, no-commitment consultation, contact [email protected].
Scott Cairns,
Managing Director